
Addis Holding announced the signing of a contract to provide offshore drilling services for the jack-up drilling rig "Shelf Drilling Fortress" in the British sector of the North Sea, in collaboration with "NEO NEXT+ Energy E&P UK Limited".
The total value of the contract is approximately 483 million riyals (equivalent to about 129 million US dollars), including the confirmed duration, the two optional extension periods, as well as mobilization and start-up fees.
The company clarified that the contract duration includes drilling two confirmed wells for a period of no less than 550 days, along with two optional extension periods, each covering one well for a duration of no less than 275 days per period, noting that platform operations and the financial impact are expected to begin during the fourth quarter of 2026.
Addis indicated that this contract reflects the strong demand environment in the North Sea, and follows its recent successes after extending the contract for the "Shelf Drilling Winner" in the Netherlands, thereby enhancing the group's strategy to secure long-term accumulated work, maintain high utilization rates for its fleet, and achieve sustainable value for shareholders.
Students from Al Yamamah University discussed the dimensions of this contract and its financial and operational implications as follows:
Breaking Down the Contract Value and Operating Margins
Student "Ghadah Alwallan" @Ghadah Alwallan opened the analysis by saying: "In my opinion, the contract value of 483 million riyals is not all confirmed revenue; it includes the two optional extension periods, mobilization fees, and start-up fees, while the currently confirmed part is drilling two wells for no less than 550 days.
Therefore, it is not enough to look at the size of the contract alone; it is more important to know the value of the confirmed part and profit margins after the costs of moving and operating the rig in the North Sea environment.
In my opinion, the success of the contract as an investment is evident if it achieves a good return even without relying on activating the extensions."
Quality of Revenue and Global Competitiveness
Student "Rimas Almashali" @Rimas Almashali commented: "This contract enhances the quality of future revenues for Addis more than it is just an increase in business volume, as it provides expected cash flows over a long period and raises the level of profit clarity for the future, which is a positive factor in the company's investment evaluation.
Moreover, the continued success in winning contracts in the North Sea reflects the company's ability to compete globally and the efficiency of its fleet and operations management.
If Addis succeeds in executing the project on schedule while maintaining operational efficiency, this could support its chances of obtaining additional contracts and enhance its position as a leading Saudi company in international drilling services."
Accumulation of Work and Investor Confidence
Student "Mohammad Alghaihab" @Mohammad Alghaihab shared his opinion, saying: "I see that the contract is positive for Addis because it adds to its contract portfolio and enhances the clarity of future revenues, which gives investors greater confidence in the continuity of the company's operations.
Additionally, having two options for extending the contract gives Addis a strategic advantage that ensures the continuity of rig operations for longer periods when activated, contributing to the expansion of accumulated contracts and supporting the sustainability of its cash flows. As the company continues to execute its projects with high operational efficiency, this type of contract enhances the clarity of the future revenue outlook, which may support a positive view of the stock in the medium and long term.
Financial Impact and Operational Efficiency
Student "Rana Alshamrani" @Rana Alshamrani concluded the analysis by highlighting the financial impact, saying: "The total value of the contract includes the two potential extension periods and mobilization fees, and the confirmed duration actually equals about half of the total duration in time, meaning the true confirmed revenue is closer to 215 to 230 million riyals, not the full announced figure.
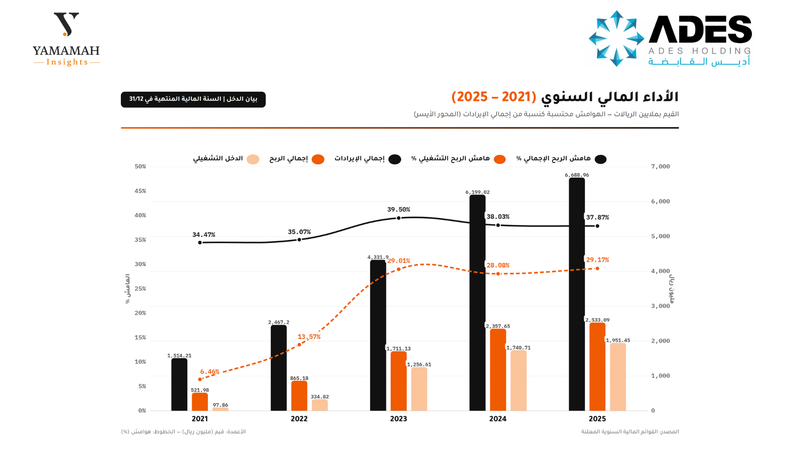
However, more important than the size of the contract is that Addis entered 2025 with an improved operating margin (29.17%) despite a near stagnation in revenues compared to 2024, indicating that the fixed cost base has been fully absorbed.
Any additional revenue from this contract - even the confirmed part alone - is expected to reflect on earnings before interest, taxes, depreciation, and amortization with higher efficiency than historical contracts.
By this standard, the contract is considered successful as an investment even in the conservative scenario that does not assume activating any extensions."
Analytical Reading of the Path of "Addis Holding"
In an analytical reading of the company's performance, financial and economic analyst "Hamad Alsaeed" @Hamad Alsaeed stated: The strategic importance of the recent contract for Addis Holding does not lie in its financial value as this contract represents less than 1.5% of the total accumulated work which reached 34.47 billion riyals by the end of March 2026. Rather, its value lies in its operational implications in solidifying the company's presence in the North Sea (coinciding with the extension of the "Winner" contract in the Netherlands), reflecting a strategic direction to diversify the asset portfolio and gradually reduce geographic concentration in the Middle East.
The financial results for the first quarter of 2026 support this reading, as the company recorded record revenues of 2.39 billion riyals with a growth of 62.6%. Operating profit also increased by 42% to reach 675.3 million riyals, maintaining an operating margin at levels of 28.3%, a trajectory consistent with the historical performance for the period (2023-2025). In terms of liquidity, operating cash flows before changes in working capital jumped by 35.8% to record 1.08 billion riyals.
Analysis of the first quarter's performance reveals a decline in the net profit margin to 10.1% due to increased financing and amortization burdens, with total debt nearing 20.5 billion riyals. Additionally, the financial impact of the new contract will not appear before the 2027 statements, as it is set to begin implementation in late 2026.
We see that this contract carries positive dimensions both qualitatively and strategically. However, the focus of attention will be on future profitability levels rather than just the pre-determined revenue growth supported by the momentum of contract accumulation. The essential information revolves around the timeline for the company's ability to convert this capital expansion into sustainable net profit margins, alongside the expected gradual decline in the cost of debt and financing burdens.
Disclaimer: This material has been prepared under the supervision of the “Yamamah Insights” editor and with the assistance of artificial intelligence tools for financial education purposes, and it does not constitute a recommendation to buy, sell, or hold any security, nor does it reflect the opinion of the platform.
 Ask Yamami

Comments (7)
No comments yet. Be the first to comment!