
Alamar Foods Company announced its preliminary financial results for the period ending June 30, 2026 (the first half), recording positive growth in sales and net profit compared with the corresponding periods of the previous year.
The company explained in its published statement that sales achieved a significant increase during the second quarter and the first half, mainly due to the positive impact of marketing initiatives, continued improvement in service levels, and the absence of the seasonal effect of the holy month of Ramadan during the current quarter.
The financial and operational details showed that revenue growth was supported by strategic expansion, with the results of 29 branches in the cities of Makkah and Taif included from the fourth quarter of 2025, in addition to the results of 13 branches of the "Five Guys" brand in Saudi Arabia from April 29, 2026.
This performance had a positive impact on net profit, which increased as a result of sales growth, supported by the success of management measures aimed at enhancing the flexibility of the expense structure and achieving a better balance between variable and fixed expenses, while continuing to focus on operational excellence and service development.
The company noted that it maintained the strength and robustness of its balance sheet, supported by generating cash flows from operating activities of SAR 80.7 million during the first half. The total number of company-owned branches reached 614, while non-owned branches totaled 150 at the end of June 2026.
Students from Al Yamamah University discussed the implications of these results and their impact on Alamar’s operational efficiency and growth trajectory, as follows:
Diversifying revenue sources and expense efficiency
Student "Mays Alawi" @Mays Alawi opened the analysis by saying: "Expansion and the acquisition of the Five Guys brand represent a good strategic step for the company, particularly as they directly contributed to sales growth, enhancing opportunities to increase market share and diversify revenue sources.
As for expenses, the results appear positive: operating profit rose by approximately 28%, a rate exceeding sales growth. This means the company succeeded in achieving growth while effectively controlling expenses.
Recording SAR 80.7 million in operating cash flows alongside profit growth also provides a reassuring indicator for investors. The challenge remains their ability to maintain this growth rate in the coming periods."
Growth quality and cash-flow strength
Student "Faisal Alqahtani" @فيصل القحطاني shared his view, saying: "Alamar’s first-half results give a positive impression. Growth was not limited to revenue; it was accompanied by a clear improvement in operating profitability and net profit, indicating that the expansion is beginning to translate into actual improvements in operational efficiency, rather than merely a numerical increase in the number of branches.
The acquisition of Five Guys and the addition of branches in Makkah and Taif also broaden the revenue base and enhance brand diversification.
Operating cash flows of SAR 80.7 million represent a key strength, giving the company greater ability to finance its expansion without heavy reliance on external financing.
Overall, the company’s operational and financial outlook is improving. If this upward trend continues, it could enhance the stock’s attractiveness over the medium and long term."
Strategic expansion and cost management
Student @شهد المحيسن explained: "The company’s results reflect a positive picture of its overall performance, particularly since sales growth coincided with an increase in operating profit and improved cash flows, confirming that the expansion was accompanied by sound cost management.
The recent acquisition and increase in the number of branches also provide the company with a greater opportunity to expand its market share. However, the long-term success of this expansion remains dependent on maintaining profit margins and avoiding any increase in operating costs that could limit the positive impact of growth."
Profitability sustainability and operational efficiency
Student "Rimas Almashali" @Rimas Almashali commented: "Alamar’s expansion and addition of brands such as Five Guys have clearly contributed to sales growth.
With operating profit and cash flows rising, the most important issue now is the company’s ability to maintain cost efficiency and convert this horizontal expansion into sustainable profitability growth."
Operational growth and expansion financing
Student @فهد الطيب added: "The first-half results give a positive impression. More important than revenue growth is the company’s ability to translate this growth into profitability and cash flows.
The operating profit increase outpacing sales growth reflects a notable improvement in operational efficiency and effective expense control. While expansion represents an additional growth driver, strong operating cash flows are the standout point because they provide comfortable financial room to fund expansion and reduce reliance on debt.
Accordingly, the continuation of operating cash-flow growth alongside improved margins will be the true driver of the company’s potential future revaluation."
Efficiency in cost structure
For her part, student "Arwa Alhuwaiti" @Arwa Alhuwaiti said: "Alamar Foods’ ability to increase operating profit by approximately 28% despite continued branch expansion reflects a clear improvement in expense-management efficiency.
Profitability growing at a faster pace than revenue is a positive indicator of improving operating margins and the company’s benefit from its cost-restructuring efforts.
If management continues to achieve this delicate balance between expansion requirements and expense control, it will be a key support for sustainable long-term financial growth."
Like-for-like sales growth (LFL)
Student "Ghadah Alwallan" @Ghadah Alwallan pointed to a key issue, saying: "What stands out most is the coincidence of revenue growth with a substantial increase in the number of branches through acquisitions.
To accurately assess the quality of this growth going forward, it will be essential to monitor sales performance at existing branches themselves, rather than focusing solely on total sales growth.
Acquisitions naturally increase revenue, but continued sales growth at older branches provides a stronger indication of underlying demand improvement. In that case, expansion will be more capable of creating genuine value for shareholders."
Cost efficiency and strategic expansion
Student "Alia Alanazi" @Alia Alanazi explained in her reading of the results: "The company’s results are positive because growth was not limited to revenue; it was also clearly reflected in operating profit, providing a reliable indicator of improved expense and cost-management efficiency.
Although the acquisition of the Five Guys brand is a successful step toward diversifying the company’s portfolio and increasing its market share, the key issue in the coming periods will be the ability of the new branches to achieve sustainable growth and profitability. A numerical increase in the number of branches alone is not sufficient to judge the success of the expansion. In addition, operating cash flows of SAR 80.7 million represent a strength supporting the expansion.
What draws attention is that operating profit for the quarter grew at a rate exceeding the growth of net profit. This calls for examining the other factors and expenses that affected net profit to assess the stock’s attractiveness based on continued earnings growth without an excessive increase in expansion costs."
Portfolio diversification and cash generation
Student "Jumana Alshehri" @Jumana Alshehri shared her opinion, saying: "The first-half results were positive, particularly as sales growth coincided with expansion efforts and the acquisition of Five Guys, enhancing opportunities to diversify the portfolio and increase market share.
The 27.98% increase in operating profit indicates that growth did not come at the expense of efficiency; rather, it was accompanied by a tangible improvement in expense management.
Strong operating cash flows are evidence of the core business’s ability to generate cash, providing the company with a favorable opportunity for future growth, provided that the performance of new branches and profit margins are monitored to ensure the sustainability of this trajectory."
Growth quality and operating leverage
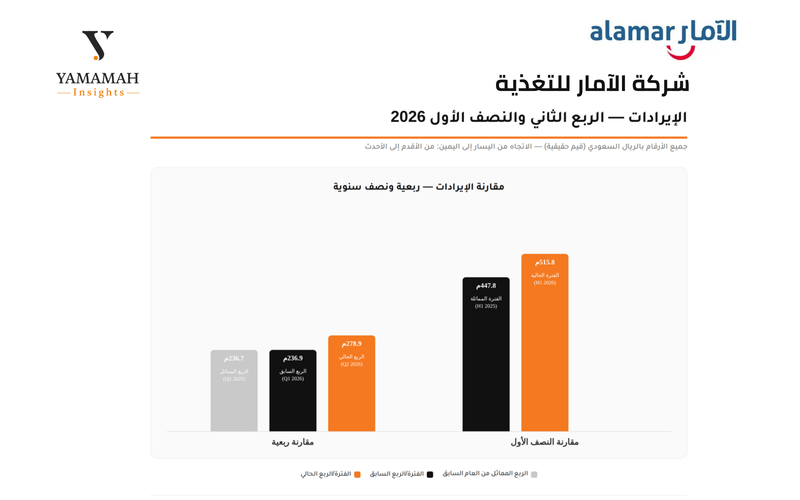
Student "Mohammad Alghaihab" @Mohammad Alghaihab noted that the results reflect a clear improvement in growth quality, saying: "Alamar Foods’ revenue rose to SAR 515.8 million from SAR 447.8 million, an increase of approximately 15.2%, driven by expansion and the addition of new branches.
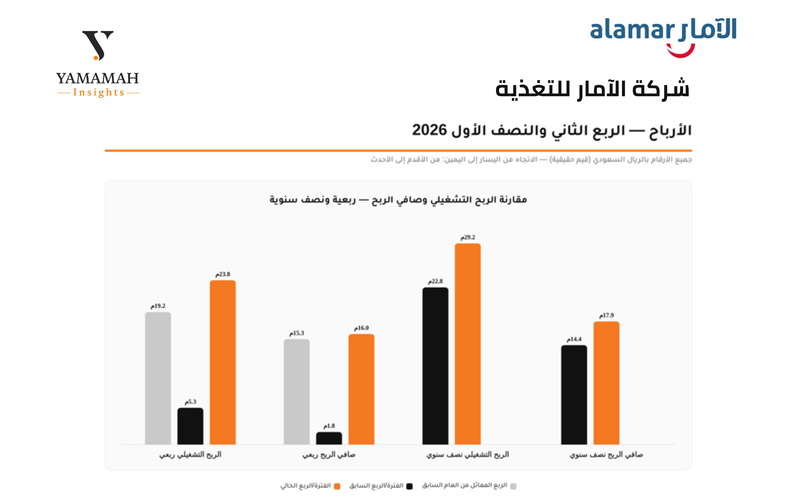
More importantly, operating profit increased at a faster pace to reach SAR 29.2 million, compared with SAR 22.8 million, confirming improved operating leverage and expense-management efficiency.
Meanwhile, net profit increased to SAR 17.9 million—approximately 24%—outpacing revenue growth and giving these results a high degree of financial quality, particularly as the branch network expanded to 764 branches in total.
The key issue for investors to monitor remains management’s ability to convert sales growth into sustainable profits and cash flows while maintaining profit margins."
Financial pressures and the test of organic growth
In a deeper analysis, student "Rana Alshamrani" @Rana Alshamrani explained: "Despite the positive operational performance, this improvement was not fully reflected in net profitability.
Although quarterly operating profit grew by 24%, the net profit margin contracted from 6.46% to 5.74%, despite revenue growth of 17.8% and an improvement in the operating margin from 8.11% to 8.53%. This indicates pressure in items below operating profit that limited the extent to which this improvement reached net profit.
Moreover, a significant portion of the expansion came through acquisitions rather than organic growth—22 new branches compared with 42 acquired branches.
Therefore, testing the sustainability of growth in the coming quarters will depend on monitoring the performance of new branches after the initial operating phase and tracking same-store sales to determine whether growth reflects an underlying improvement in demand.
Non-operating items such as financing costs and zakat must also be monitored to determine whether the contraction in the net profit margin is temporary or ongoing."
Growth quality between operational efficiency and financing pressures
In an analytical review of the company’s performance, financial and economic analyst "Hamad Alsaeed" @Hamad Alsaeed explains: Alamar’s first-half 2026 results present a financial picture combining rapid growth with a real improvement in operational efficiency. The company recorded a 23.8% jump in net profit to SAR 17.86 million, supported by 15.2% revenue growth. This momentum is the direct result of an aggressive acquisition strategy that added 42 acquired branches, alongside 22 branches from organic growth, increasing the number of company-owned branches to 614.
Notably, operating profit did not decline; rather, it grew 27.98% year on year in the first half, exceeding even the pace of revenue growth—an indication of a genuine improvement in operating margins despite the integration costs associated with the expansion. However, this operational improvement was not fully reflected in net profit, particularly in the second quarter, when operating income grew 24% quarter on quarter compared with only 4.8% growth in net profit. This suggests that an item below operating income—such as financing costs related to acquisition debt or zakat—absorbed part of the quarter’s gains. In a related development, shareholders’ equity declined to SAR 286.7 million despite profit growth, which cannot be explained by cash distributions alone.
The reading of the third quarter will depend on determining the nature of the gap between operating profit growth and net profit growth, and whether it is merely a temporary acquisition cost or the beginning of a permanent financing burden associated with the integration of Five Guys.
Disclaimer: This material was prepared under the supervision of a “Yamamah Insights” editor and with the assistance of artificial intelligence tools for financial education purposes. It does not constitute a recommendation to buy, sell, or hold any security, and reflects the views of its contributors rather than those of the platform.


Comments (6)
No comments yet. Be the first to comment!