
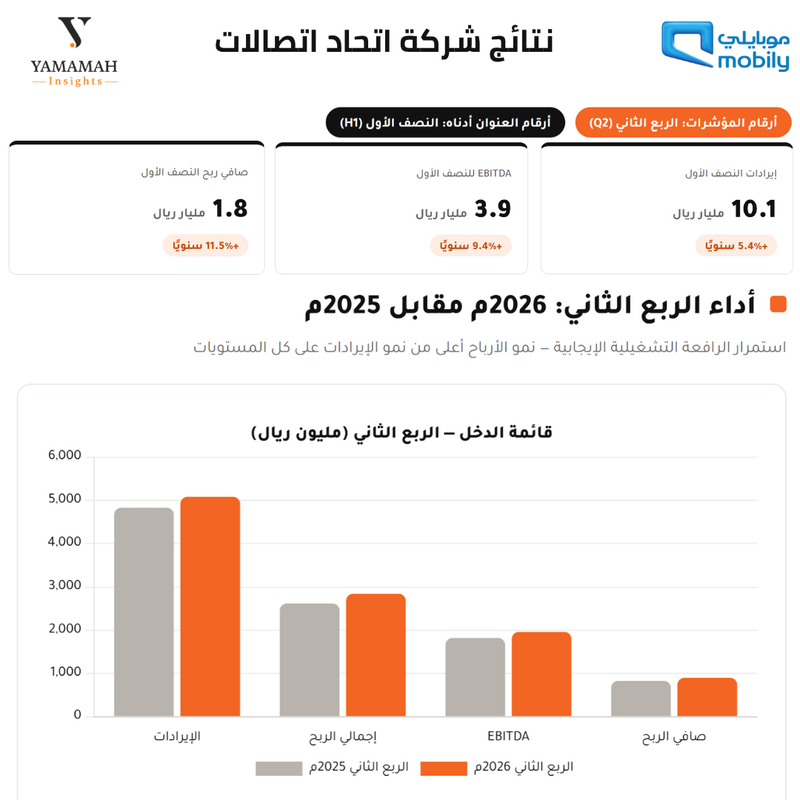
Etihad Etisalat Company (Mobily) announced its preliminary consolidated financial results for the period ending on June 30, 2026 (the first half), where it achieved a net profit of 901 million riyals for the second quarter, an increase of 8.6% compared to 830 million riyals during the same quarter of the previous year.
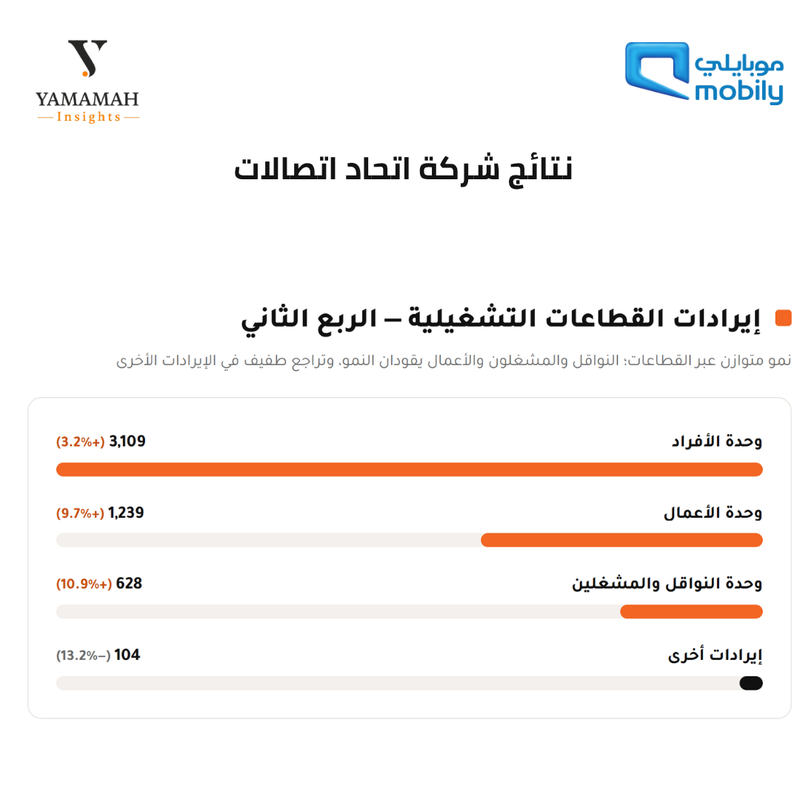
The company clarified that revenues continued to grow during the second quarter, reaching 5,080 million riyals, an increase of 5.2%, mainly due to revenue growth across all sectors and the continuous increase in the customer base.
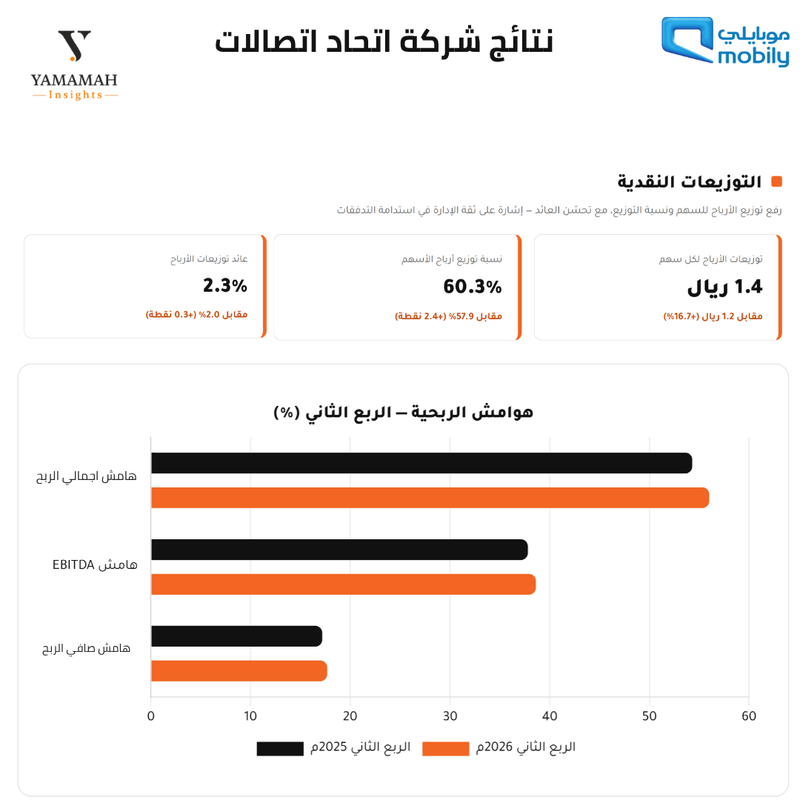
Mobily indicated that earnings before interest, taxes, depreciation, and amortization (EBITDA) grew by 7.7% to reach 1,963 million riyals, with an improvement in the profit margin to 38.6%.
This performance positively reflected on operating profits, which increased by 9.8% to record 978 million riyals during the current quarter.
Regarding the performance of the first half of 2026, the company managed to increase its revenues by 5.3% to reach 10,120 million riyals, supporting net profit growth for the period by 11.5% to reach 1,781 million riyals compared to 1,597 million riyals for the same period of the previous year.
You can view the financial results bulletin click here
Students from Al Yamamah University and financial experts discussed the dimensions of these results and their financial and operational implications as follows:
Operational Efficiency and Sustainable Growth
Student "Rimas Al Mashali" @Rimas Almashali opened the analysis by saying: "I see that Mobily's results reflect the continued strength of its operational performance, as the net profit growth (11.5%) is higher than revenue growth (5.3%), indicating an improvement in operational efficiency and increased profitability.
Moreover, revenue growth across all sectors and the increase in the customer base enhance the company's ability to achieve sustainable growth, despite rising other expenses."
Cash Flows and Profit Margins
Student "Ghadah Alwallan" @Ghadah Alwallan commented: "In my opinion, the strength of the results is not only reflected in profit growth but also in the company's ability to maintain an EBITDA margin of 38.6% despite a 56% increase in capital expenditures in the second quarter compared to the same quarter of the previous year.
This suggests that current investments have not yet affected operational efficiency, but the real test will be the ability of these investments to increase free cash flows in the future, not just accounting profits."
Diversification of Income Sources and Seasonal Impact
Student "Mohammad Alghaihab" @Mohammad Alghaihab shared his opinion, saying: "In my opinion, Mobily's results are generally positive, as revenues and profits are continuously growing, indicating that the company's operations are strong.
As for the drop in the stock despite the results, I see it as due to the market expecting higher numbers, or because part of the liquidity has shifted to other sectors.
Regarding the large investments in data centers and infrastructure, while they currently pressure cash flows, if these projects succeed, they will reduce the company's reliance on mobile services and open new income sources in the long term.
Additionally, the Hajj season provided a boost to revenues, but it was accompanied by an increase in costs to prepare the networks, which is normal with increased pressure on services."
Results Match Expectations and Second Highest Quarterly Profits in 13 Years
Financial expert "Abdulaziz Khrais" commented on the financial results, saying: "Etihad Etisalat Company (Mobily) opened the telecommunications sector results for the second quarter by achieving profits of 901 million riyals, which matches the average expectations of analysts. 'Qimah Financial' was the closest among the research houses in predicting the results, expecting 906 million riyals.
Let’s take a quick look at the key figures.. The company recorded a net profit of 901 million riyals, which is the second highest net profit for the company in 13 years after the last fourth quarter, while the company's revenues exceeded 5 billion riyals, supported by an increase in the number of customers and growth in most sectors.
In related news, the company continued to distribute dividends to shareholders, as the board of directors recommended distributing dividends of 1.4 riyals per share, with the entitlement date being Thursday, July 30, 2026."
Remarkable Operational Flexibility and Short-term Expansion Challenges
In an analytical reading of the company's performance, financial and economic analyst "Hamad Alsaeed" @Hamad Alsaeed stated: The results of the second quarter of 2026 for Mobily demonstrated remarkable operational flexibility, achieving a net profit of 901 million riyals with an annual growth of 8.6%. The key point here is the company's significant ability to seize opportunities and maximize revenues during seasons such as the Hajj season, despite high competition in this sector. We see that the company succeeded in expanding its subscriber base by 16.9%, benefiting from strategic partnerships and a distinguished wholesale sales sector.
This success, supported by advanced digital solutions, directly contributed to raising the gross profit margin to 56%, which translates to high efficiency in converting dense operational activity into viable profit flows, reflected in a leap in first-half profits to reach 1.78 billion riyals.
With this outstanding performance, we note a point of caution as we observe that quarterly growth (compared to the first quarter of 2026) was modest at only 2.4% for profit and 0.8% for revenues. This relative slowdown is attributed to the noticeable increase in capital expenditures on a quarterly basis, and depreciation and amortization expenses resulting from intensive investment in infrastructure, 5G networks, and data centers.
Although these investments are necessary to ensure future growth, they may impose temporary pressures on profit margins and free cash flows in the short term, requiring close monitoring of how quickly these capital assets can be converted into tangible cash returns in the coming periods.
Disclaimer: This material has been prepared under the supervision of the “Yamamah Insights” editor and with the assistance of artificial intelligence tools for educational financial purposes, and does not constitute a recommendation to buy, sell, or hold any security, and it reflects the opinions of its authors and not the platform's opinion.
 Ask Yamami

Comments (8)
No comments yet. Be the first to comment!