
Saudi Aramco Base Oils - Luberef announced its preliminary financial results for the period ending on June 30, 2026 (for six months).
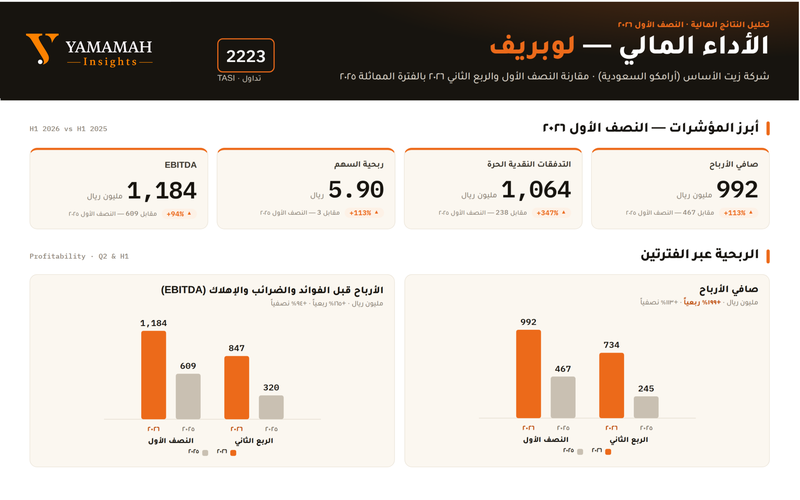
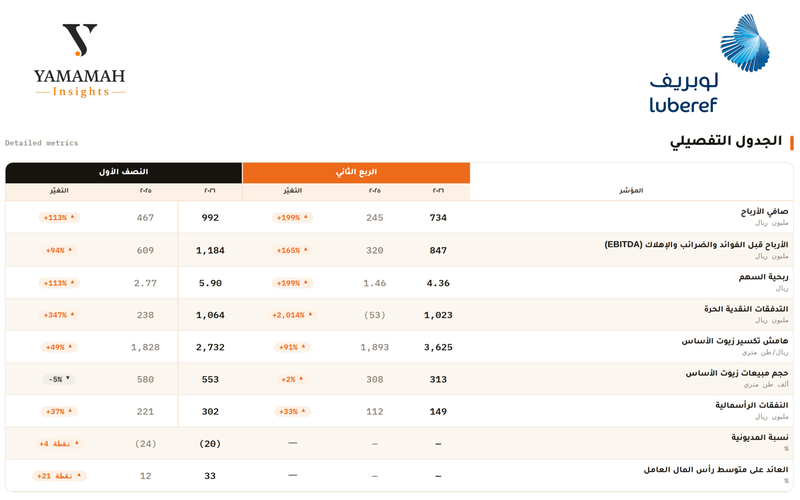
The company recorded its second highest profits in its history for the second quarter, amounting to 734 million riyals, while revenues surged to a record level exceeding 3.4 billion riyals, driven by rising prices and cracking margins of base oils and by-products.
In light of these strong results, the board of directors recommended a cash dividend of 4 riyals per share totaling 673 million riyals, reflecting the robustness of its financial position.
Students from Al Yamamah University discussed the financial and operational dimensions of these results and their implications for the sustainability of the company's operations, as follows:
Operational Efficiency Converts Profits into Free Cash Flows
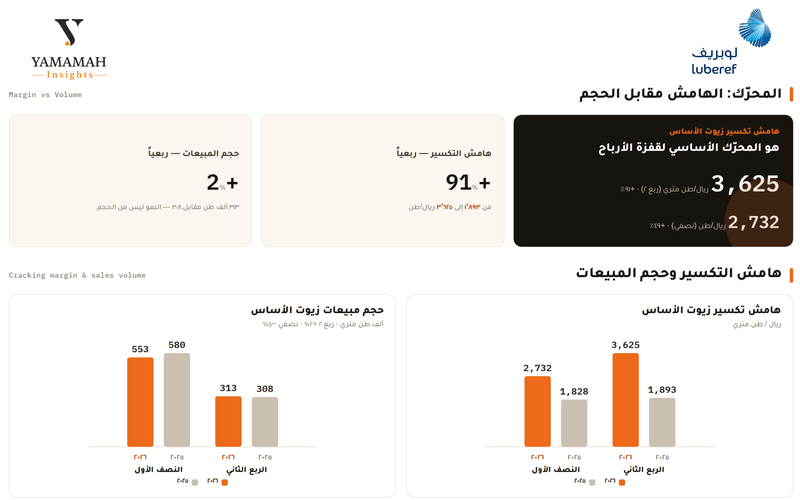
Student @Fahad Al-Tayeb explained that the results do not merely reflect a temporary benefit from rising prices, but show a clear improvement in operational efficiency. He noted that despite revenues increasing by about 52%, the remarkable aspect is the net profit jump of about 199%, which means achieving higher profit margins from every ton sold, as evidenced by the increase in the cracking margin of base oils by 91%.
He added that exceeding free cash flows of one billion riyals gives the company greater flexibility to finance expansions, sustain distributions, and reduce the need for borrowing, questioning the company's ability to maintain these margins if the market cycle changes.
Flexibility of the Business Model and Its Ability to Compensate for Declining Secondary Margins
Student Rimas Al-Mashali @Rimas Almashali viewed the results as reflecting a strong improvement in operational performance, where profit growth was driven by improved base oil margins and increased sales.
She confirmed that the company demonstrated flexibility in compensating for the decline in margins of some secondary products, reflecting the strength of its business model.
She considered that the increase in earnings per share and the soundness of the financial report enhance investor confidence, emphasizing the importance of maintaining these margins to ensure sustainable growth.
Profit Growth Exceeds Revenue Growth Thanks to Improved Selling Margins
Student Mohammad Al-Ghaihab @Mohammad Alghaihab pointed out that the results were strong with profits doubling significantly supported by improved base oil margins, rising selling prices, and sales volumes, which reflected on revenue growth and earnings per share.
He noted that profit growth was much higher than revenue growth, indicating an improvement in operational efficiency and benefiting from margin improvements rather than just increased sales, making the results strong in terms of profitability.
Operational Performance as a Key Driver of Profit and Sales Growth
Student @Shahad Al-Muhaysin indicated that the results reflect a clear improvement in operational performance, with profit growth coinciding with rising revenues, improved base oil margins, and increased quantities sold.
She clarified that the growth did not rely solely on price increases but was accompanied by improvements in the activity itself, noting that the significant increase in earnings per share enhances the company's attractiveness to investors, especially if margins remain at good levels.
Quality of Profits and Stability of Performance Enhance Positive Outlook for the Stock
Student Jumana Al-Shehri @Jumana Alshehri confirmed that the profit surge is primarily due to improved base oil margins, indicating the company's ability to achieve higher profit margins. She explained that revenue growth results from both rising selling prices and increased quantities sold together.
She added that the issuance of the auditor's report with an unmodified opinion gives investors greater confidence in the quality of profits and stability of operational performance, supporting the continuity of cash distributions in the future.
Exploiting Market Crises and Recording Record Revenues Reflect on Distributions
Expert Professor Abdulaziz Khrais believes that Luberef has managed to exploit the crisis to its advantage, recording profits that are the second highest in the company's history for the second quarter of 2026 amounting to 734 million riyals.
Khrais explained that the company's revenues reached a record level exceeding 3.4 billion riyals, as the rise in prices of base oils and secondary products contributed to the increase in revenues, while the rise in cracking margins of base oils was a significant factor in the increase in net profit. Additionally, he noted the board's recommendation to distribute cash dividends to shareholders of (4 riyals) per share for the first half, totaling 673 million riyals, indicating that this percentage is considered high compared to the company's usual distributions, congratulating the company's investors on these profits and cash distributions.
Exceptional Profits Below Expectations.. and Valuation Ignores Structural Challenges
In an analytical reading of the company's performance, financial and economic analyst Hamad Al-Saeed @Hamad Al-Saeed stated: The second quarter results showed a strong jump in net profits reaching 734 million riyals with an annual growth of 199%. Despite these exceptional figures, the results came below market expectations that bet on profits approaching one billion riyals, specifically the estimates of Al Ahli Financial amounting to 1.06 billion riyals.
This discrepancy is mainly due to the fact that the cracking margins of base oils, despite reaching record levels of 967 dollars per ton or equivalent to 3,625 riyals, did not meet the optimistic estimates of 1,073 dollars. Additionally, there was a sudden drop in the margins of secondary products, which approached the breakeven point instead of the positive expectations.
From an operational perspective, the management's success in strategically postponing scheduled closures to capitalize on peak margins is commendable, which raised quarterly sales volumes to 313 thousand tons, exceeding the estimates of 294 thousand, helping to mitigate the impact of the semi-annual decline of 5%.
Investment-wise, several analysts believe that the stock is currently trading at price levels that reflect the sustainability of this boom and is moving away from the fair valuation consensus and targets of research houses. Despite the strong cash position and massive free cash flow that ensures generous distributions and funds expansions in the Yanbu 2 project, the current valuation ignores the inevitability of normalizing margins in the future and the structural pressures from electric vehicles, which justifies the cautious outlook of some research houses.

Comments (5)
No comments yet. Be the first to comment!