

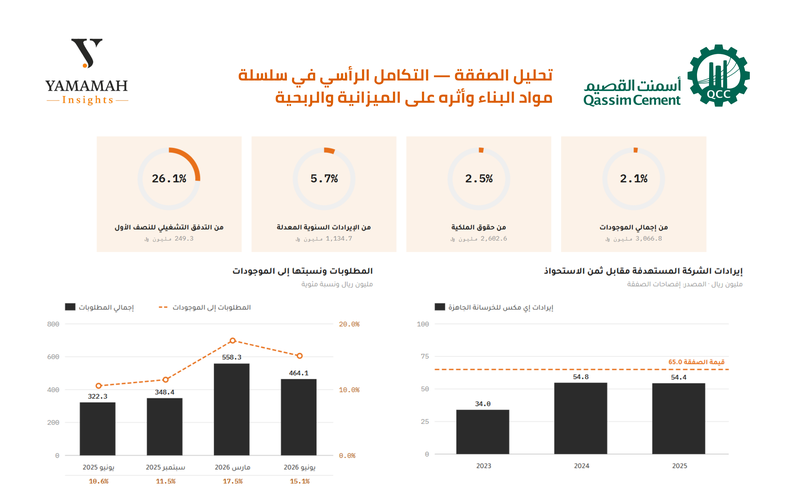
Qassim Cement Company has entered into a share sale and purchase agreement to acquire 100% of the share capital of A Mix Ready-Mix Concrete Company, for a total consideration of SAR 65 million, payable in three installments and financed through existing credit facilities that comply with Islamic Sharia principles.
This strategic step reflects the group’s pursuit of strengthening the building materials value chain through vertical integration. Completion of the transaction and the transfer of share ownership remain subject to fulfilling regulatory requirements and obtaining the General Authority for Competition’s non-objection, along with completing the disclosure of all individual selling shareholders involved in the transaction.
The transaction is expected to contribute to diversifying the company’s revenue sources and expanding its ready-mix concrete manufacturing and marketing activities, building on the target company’s operating performance, which recorded revenue of SAR 54.4 million in 2025. The latest supplementary disclosures will not result in any additional financial impact on transaction costs.
Students of Al Yamamah University discussed the strategic and financial dimensions of this acquisition and its implications for the building materials sector as follows:
Strengthening vertical integration and diversifying revenue sources
Student "ريماس المشعلي"@Rimas Almashali explained her view, saying: "I believe this acquisition represents a strategic step for Qassim Cement, as it expands the scope of its business from cement production to include ready-mix concrete. This will support the company’s ability to meet growing demand in the construction sector and diversify its revenue sources over the long term."
Balancing short-term financial effects with future integration returns
Student "البتول بديري"@Albatool Bedairi outlined the deal’s dimensions, saying: "In the short term, completing the transaction may increase the company’s assets and liabilities as well as financing costs. In the long term, however, successful integration and strong growth by A Mix will boost revenue and profits, enabling the company to maximize the benefits of the value chain, provided the expected returns are achieved."
Securing sales outlets and enhancing competitiveness in major projects
Student "فيّ الدوسري"@Fay Aldossari shared her analysis, saying: "The company’s transformation into a finished-concrete producer will secure continuous sales outlets for its cement products and protect its market share. The deal’s valuation of SAR 65 million also remains excellent compared with recorded revenue of (SAR 54 million), while payment through existing facilities reduces cash-flow pressure. The initial financial impact will appear through higher revenue, eventually leading to higher profit margins and more stable cash flows, giving the company an advantage in providing integrated concrete solutions for Vision projects and infrastructure initiatives."
Financing flexibility and readiness for infrastructure projects
Student "جمانه الشهري" @Jumana Alshehri highlighted the operational aspects, saying: "The acquisition reduces the company’s reliance on standalone cement sales by entering the concrete sector. Paying the transaction value in three installments through existing bank facilities provides financial flexibility without placing significant obligations on the balance sheet. Despite the temporary costs of integration, the expansion strengthens cash flows and enhances readiness to capture opportunities in major urban development projects."
The importance of operational integration and leveraging the customer base
Colleague "لجين القرشي"@Lujain Algorashi highlighted operating efficiency, saying: "Expansion into ready-mix concrete strengthens the company’s position within the value chain. The transaction value appears reasonable compared with the target company’s revenue, but the key measure of success lies in achieving genuine operational integration and leveraging the existing customer base, while noting that payment through existing facilities reduces direct liquidity pressure."
Financial valuation and the return-on-investment test
Student "أروى الحويطي" @Arwa Alhuwaiti pointed to the valuation criteria, saying: "The transaction value appears reasonable at first glance given A Mix’s annual revenue of SAR 54 million relative to the purchase price. The payment structure of three installments also eases cash-flow pressures, but the final assessment of the acquisition’s success depends on the deal’s ability to create genuine value for Qassim Cement’s profits and generate an appropriate return on investment."
Capitalizing on the construction boom and converting expansion into profits
Student "دينا العرجاني" @Dina Alarjani added: "This step is positive because it reduces total reliance on cement sales and opens the door to the ready-mix concrete market. In addition to the suitable payment structure, the key test remains management’s ability to convert this expansion into actual operating profits by benefiting from the current construction boom."
Financial solvency and limited impact on the balance sheet
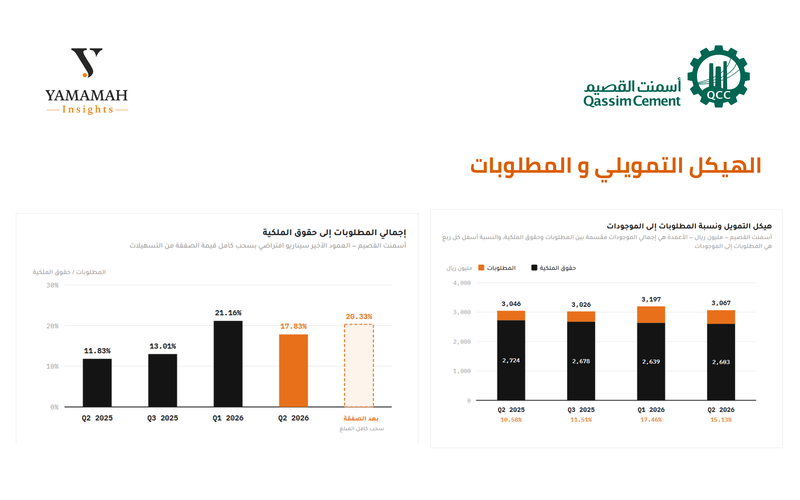
Student "يزن الحمود" @Yazan Hamoud analyzed the financial figures, saying: "The transaction is relatively small compared with the company’s total assets; SAR 65 million represents approximately 2.1% of assets and 2.5% of shareholders’ equity. Even with the use of facilities, the liabilities-to-equity ratio would rise only slightly, from 17.8% to just 20.3%. The core opportunity lies in linking cement production with ready-mix concrete to meet the requirements of infrastructure projects."
Strengthening market share in the building materials supply chain
Student "@ثناء الشايب" highlighted the importance of diversification, saying: "The acquisition strengthens integration between the cement and concrete businesses, reducing the risks of relying on a single revenue source. With the continued momentum in real estate and infrastructure projects, this expansion gives the company a greater opportunity to increase its market share within the building materials supply chain."
Achieving sustainable growth through integrated concrete solutions
Student "محمد المسعود" said: "Vertical integration through the A Mix transaction diversifies revenue and improves operating efficiency over the long term. Structuring payment in three installments through existing facilities balances the purchase with the preservation of liquidity, giving the company greater capacity to provide integrated solutions aligned with the construction boom and major projects."
Valuation multiples and the impact on operating margins
Student "أمل منسي" @Amal Mansi summarized the valuation aspect, saying: "The transaction achieves vertical integration that increases cement and concrete sales together, and the valuation was fair at a sales multiple of approximately 1.2 times. Flexible financing through existing facilities did not require substantial debt, while the financial impact will be reflected in higher operating revenue with a limited increase in liabilities, strengthening the company’s competitive position."
Securing direct demand and reducing price volatility
Student "فهد الرويشد" @Fahad Alruwaished pointed to the market-protection angle, saying: "Qassim Cement’s 100% acquisition guarantees direct and continuous sales outlets for its core product, which protects its market share and increases demand for its production given the high consumption of ready-mix concrete. This diversification also reduces the risks of price and demand volatility in the construction market."
Operational integration as a strategic distribution channel
Student "شهد الخميس"@Shahad Alkhamis emphasized the importance of asset management, saying: "The transaction is reasonably sized and does not put pressure on the balance sheet. The real wager is not the purchase price so much as the ability to achieve operational integration of A Mix and turn it into a distribution channel that supports cement sales and diversifies revenue, thereby increasing competitiveness in major contracts."
Financing flexibility and avoiding additional loans
Student "غاده الوعلان" @Ghadah Alwallan said: "The transaction value of SAR 65 million is consistent with A Mix’s annual revenue. The practical advantage lies in paying the amount in three installments using existing bank facilities, sparing the company the need to arrange significant additional financing and giving it financing flexibility."
Linking the target company’s profitability to the acquisition value
Student "محمد الغيهب" @Mohammad Alghaihab concluded the discussion, saying: "The move represents a logical transition from selling raw materials to selling a finished product (ready-mix concrete). Operational success would provide greater control over the value chain and a better profit margin, but the most important evaluation criterion is the extent to which A Mix’s net profit—not just its revenue—can justify the acquisition value."
Major project opportunities and investment evaluation
In an analytical reading, financial and economic analyst "حمد السعيد" @Hamad Alsaeed adds: Perhaps the most important aspect of Qassim Cement’s acquisition of A Mix Ready-Mix Concrete for SAR 65 million is that it represents a shift from selling raw materials to selling a finished product at the project site, rather than a growth transaction. Its value amounts to only 2.5% of the company’s shareholders’ equity, while the target’s revenue does not exceed 4.8% of the acquirer’s annual revenue.
The transaction comes at a time when the Kingdom awarded construction contracts worth more than SAR 30 billion in May 2026 alone, according to the Saudi Contractors Authority, alongside a non-deferrable program involving 11 stadiums and approximately 230,000 hotel rooms in preparation for the 2034 World Cup, as well as New Murabba, Diriyah, and Expo 2030. Ready-mix concrete—not raw cement—is what contractors purchase for these projects.
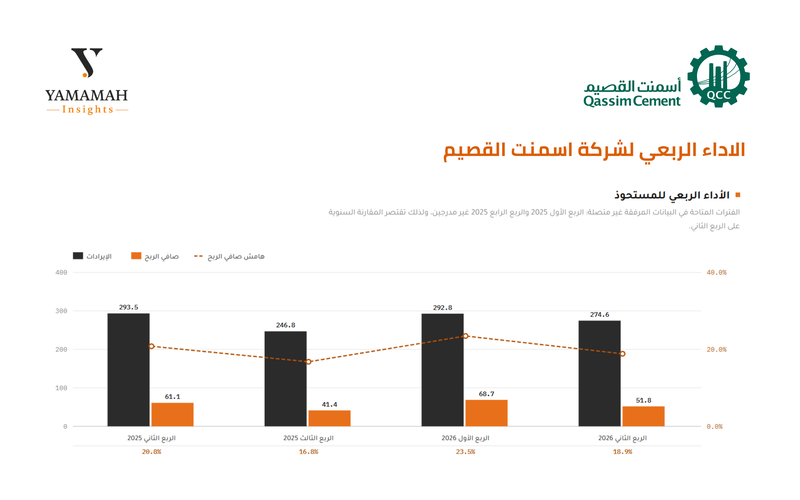
The impact on profitability is expected to remain limited, and the deal’s viability will be determined by the margin achieved by the target after consolidation and by the difference between the amount paid and its net assets, which will appear under goodwill.
 Ask Yamami
Comments (6)
No comments yet. Be the first to comment!