
ADES Holding Company announced that its subsidiary, ADES Saudi Limited, has completed the full acquisition of Saipem Arabia Company Limited for a total consideration of SAR 1.07 billion (US$285 million), financed through available cash and existing credit facilities.
The deal includes the acquisition of five premium jack-up drilling rigs (three owned and two leased). Four operate in Saudi Arabia, while the fifth operates in Mexico under an existing contract.
The company said the acquisition adds approximately SAR 3.8 billion (US$1 billion) to its backlog, supporting greater visibility into long-term revenue and cash flows as part of its strategy of disciplined expansion through assets with existing contracts.
Against the backdrop of measuring the financial impact and expanding the offshore fleet, students at Al Yamamah University discussed the decision’s implications for the sector and the company’s future growth, as follows:
Boosting operational efficiency and accelerating growth through existing assets
Student “Rand Alkhalaf”@Rand Alkhalaf opened the analysis, saying: “I believe the acquisition gives ADES an opportunity to increase its revenue and cash flows by adding assets ready for operation, rather than building new ones from scratch. Expanding through acquisitions also helps the company grow its fleet and strengthen its competitive position.
As for investing in oil and gas, I believe there are still growth opportunities despite the global shift toward renewable energy, particularly given the continued demand for oil and gas. International expansion can support the company by diversifying its revenue sources and increasing the contribution of Saudi companies to global markets.”
Balancing cash flows and financial leverage risks
Student “Yazan Hamoud” @Yazan Hamoud explained the implications of the deal, saying: “I believe the acquisition is a good move because it adds assets ready for operation and increases revenue without waiting for new rigs to be built.
However, it is important to be mindful of rising debt and financial leverage. The deal’s success therefore depends on the new rigs’ ability to generate cash flows and profits that cover the cost of the acquisition and its financing.”
Contract readiness and effective cost management
Student “Dina Alarjani” @Dina Alarjani shared her analysis, saying: “In my view, ADES’s acquisition is a good move because it adds assets operating under existing contracts, which could have a rapid impact on revenue and cash flows.
I also see its expansion in oil and gas as a growth opportunity, despite the shift toward renewable energy, because demand for conventional energy remains steady. But the deal’s success depends on managing the assets and costs efficiently.”
Accelerating expansion and strengthening international presence
Student “Rabiah Almugait” @Rabiah Almugait shared her perspective, saying: “I believe adding five drilling rigs could boost ADES’s revenue and cash flows, particularly if the rigs are placed on new or existing contracts.
I believe acquiring ready-to-operate assets saves the company a great deal of time and effort, but ultimately, it depends on its ability to operate and manage them well.
As for oil and gas, I believe the sector still offers opportunities despite the major shift toward renewable energy, because demand for oil and gas remains. I also see expansion beyond Saudi Arabia as an important step for ADES: it diversifies its revenue sources, gives it a greater opportunity to establish a presence in global markets, and could have a positive impact on the local economy.”
Sustainable cash flows and geographic risk diversification
Student @ثناء الشايب emphasized the importance of the operating model, saying: “What stands out about ADES’s deal is that the company is not simply expanding by increasing the number of rigs; it is also saving time by acquiring existing assets that are ready to operate.
In my view, the success of this strategy depends on the company’s ability to turn this rapid expansion into sustainable cash flows. Its global presence, in particular, gives it an opportunity to diversify its revenue sources and reduce its reliance on a single market.”
Strengthening competitiveness and expanding abroad
Student “Jumana Alshahri” @Jumana Alshehri added her analysis, saying: “I believe the acquisition is an important step for ADES because it adds five drilling rigs and expands the company’s operations, which could support revenue and cash flows as the assets begin operating and are integrated. The strategy of acquiring existing assets also helps the company expand faster than building new assets from scratch, and strengthens its competitive position.
As for expansion in oil and gas, I believe demand for drilling services remains steady, so this could be a growth opportunity despite the global energy transition. As ADES expands abroad, diversifying revenue sources and entering global markets could support the company’s growth and strengthen the global presence of Saudi companies.”
Managing the risks of the energy mix transition
Student “Albatool Bedairi” @Albatool Bedairi highlighted the strategic trade-offs, saying: “I believe this expansion represents an opportunity tied to continued demand for drilling services, but it also carries long-term risks associated with changes to the energy mix. Existing contracts and high utilization of offshore drilling rigs help mitigate some of these risks.”
Immediate financial impact and backlog growth
Student “Fahad Alruwaished” @Fahad Alruwaished commented on the financial value, saying: “In my opinion, ADES’s SAR 1.07 billion acquisition of Saipem Arabia is a masterstroke, and its financial impact will be swift and significant. The five acquired rigs are operational and already tied to existing contracts, which means revenue and cash flows will start coming into the company immediately, without any waiting.
Moreover, adding SAR 3.8 billion to its backlog gives ADES excellent stability and sustainability in its revenue over the long term. It more than covers the cost of the financing and credit facilities used for the deal.”
Integration challenges and protecting profit margins
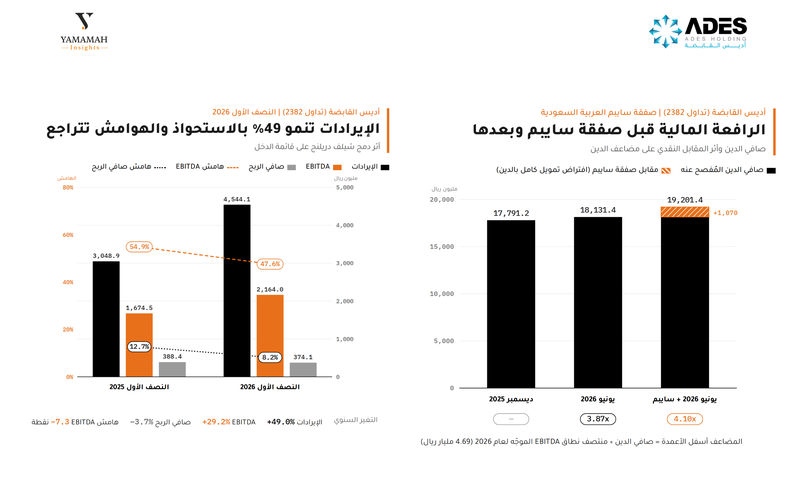
Student “Ghadah Alwallan” @Ghadah Alwallan warned of operational challenges, saying: “I believe the real challenge of the deal will emerge after integration, particularly since ADES entered 2026 with strong revenue growth but a decline in its EBITDA margin and an increase in net debt.
The acquisition’s success should therefore not be measured only by the addition of SAR 3.8 billion to the backlog, but by the new rigs’ ability to generate sufficient profits and cash flows to improve the return on capital without putting additional pressure on margins and debt.”
Increasing productivity and improving asset returns
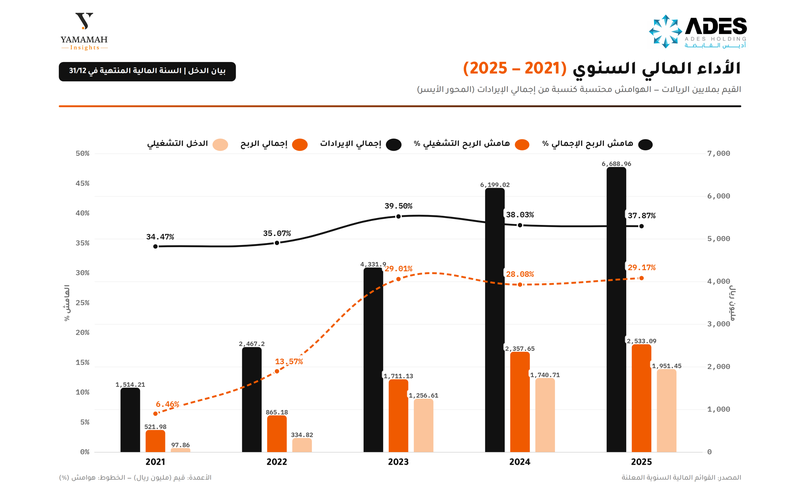
Student “Rimas Almashali” @Rimas Almashali focused on asset efficiency, saying: “I note that Saipem Arabia’s revenue fell from approximately SAR 870 million in 2023 to SAR 636 million in 2025. So, what matters most to me is not the number of rigs added, but whether ADES can increase their productivity following the acquisition. If it can improve utilization of these assets and generate higher returns from them than they did previously, then the acquisition will truly have created value rather than simply expanded the company’s size.”
Governance and the legal aspects of acquisition contracts
Student “Ryouf Alsewailim” @Ryouf Alsewailim outlined the regulatory perspective, saying: “From a legal and regulatory standpoint on acquisitions and corporate governance, the completion of the Sale and Purchase Agreement (SPA) confirms that all conditions precedent to closing have been met. This means legal ownership of the shares in ‘Saipem Saudi Arabia’ has transferred to ADES Saudi Limited, resulting in the consolidation of financial statements and immediate legal and operational control of the rigs.
Risk management for hybrid contracts—which combine owned and leased assets, in this case three owned rigs and two leased rigs—also requires the careful transfer of existing operating contracts and lease agreements to ensure cash flows continue without contractual disputes or operational interruptions.
In addition, compliance and expansion through subsidiaries, including the use of an indirectly wholly owned subsidiary to execute the acquisition, represent a flexible approach to governance and investment. This helps contain risks, facilitates financing, and allocates legal obligations in a way that supports the company’s domestic and international expansion.”
Assessing the acquisition’s value relative to its investment cost
Student “Arwa Alhuwaiti” @Arwa Alhuwaiti pointed to the financial indicators, saying: “From a financial perspective, I believe the deal could give ADES a clear boost to growth, particularly because the acquisition adds five jack-up drilling rigs and increases the company’s backlog by approximately SAR 3.8 billion.
The most important point is that the acquired assets are already operational, so the company does not need to start building a new fleet from scratch. But in my view, the deal’s success will become clearer by tracking the revenue, cash flows, and profit margins generated by operating the rigs and comparing them with the acquisition cost of approximately SAR 1.07 billion.”
Economic impact and international operational influence
Student “Ahmed Aljedaan” described the national implications, saying: “My perspective on the fourth theme is that ADES’s international expansion and its emergence as the world’s largest offshore drilling rig operator are a major milestone with a direct impact on our national economy. Profits earned from overseas operations and repatriated to Saudi Arabia contribute not to gross domestic product, but to gross national income through net factor income. This turns the company into a channel for exporting operational capital, rather than merely a domestic contractor.
Moreover, this leadership gives our national companies operational influence and bargaining power worldwide. It demonstrates that Saudi Arabia is a leader not only in oil production, but also in providing and managing logistics and technical services for the global energy sector.””
Capitalizing on operational opportunities and meeting demand
Student “Noof Alanazi”@Noof Alanazi wrote in her analysis: “I believe ADES’s acquisition is a good move because it increases the number of its rigs and expands its operations, which could help increase revenue.
Acquiring ready-to-operate assets also helps the company expand faster and strengthen its competitive position. With continued demand for oil and gas, this could be a growth opportunity, particularly if the company can operate the rigs efficiently and generate good returns.”
Capital efficiency and seizing investment gaps
Student “Fay Aldossari” @Fay Aldossari emphasized the strategic implications, saying: “The investment strategy is a smart move that enhances capital efficiency: acquiring existing assets is faster and less expensive than building new rigs, strengthening the company’s competitive position. ADES’s investment in conventional energy is not a risk but a strategic opportunity: it capitalizes on declining global investment in the sector to meet ongoing demand for oil and gas and generate attractive returns.
ADES’s moves reflect a balanced strategic approach that combines rapid growth, cost reduction, and leveraging the global financing gap to strengthen national economic power.”
Turning assets into rapid cash flows
Student “Lujain Algorashi” @Lujain Algorashi offered her analysis, saying: “I believe the deal is about more than adding five rigs to the fleet; it expands the company’s ability to turn existing assets into revenue and cash flows more quickly. Acquiring existing rigs and companies gives it greater scope to expand without having to build new assets from scratch.
With continued demand for oil and gas, this approach could support the company’s growth, especially as it expands into foreign markets and strengthens the global presence of Saudi companies. However, its success depends on management’s ability to operate these assets efficiently and generate returns commensurate with the scale of the investment.”
Macroeconomic impact and the challenge of converting contracts into free cash flow
In an analytical assessment, financial and economic analyst Hamad Alsaeed @Hamad Alsaeed adds: With the completion of the acquisition of five offshore rigs for US$285 million, ADES’s fleet grows to 128 units, and its operations extend from Nigeria to the North Sea and Mexico. Returns from these Saudi-owned assets operating abroad do not contribute to gross domestic product; rather, they are reflected in gross national income through net factor income. The company thus becomes a channel for exporting operational capital, rather than merely a domestic contractor.
Perhaps the most notable development in the second quarter is that revenue rose 36.4% to SAR 2.15 billion, while net profit fell 30.5% to SAR 133.3 million. The gap reveals the nature of a sector reliant on depreciation, financing, and operating crews—costs that do not fall when a rig is idle—so margins fluctuate more sharply than revenue.
Maintaining its guidance for earnings before interest, taxes, depreciation, and amortization at SAR 4.50–4.87 billion after operations resumed points to a bet on acquisition synergies. Acquiring assets with existing contracts and a SAR 3.8 billion backlog reduces operational risk, but depreciation and financing costs weigh before the benefits flow through to earnings. Ultimately, success will depend on the fleet’s ability to convert revenue into free cash flow.
 Ask Yamami

Comments (5)
No comments yet. Be the first to comment!