
Knowledge Economic City Company announced the signing of a strategic memorandum of understanding with Dar Al Majd Real Estate Company (Al-Majdiah) and Capital Hills Financial Company, with the aim of establishing the general framework for developing a distinctive residential and commercial project within Knowledge Economic City in Medina.
The company explained in its statement that the project will be implemented through the establishment of a closed-ended real estate investment fund. Knowledge Economic City will contribute the project land as an in-kind contribution, giving it approximately 80% ownership of the fund, while Al-Majdiah will contribute cash for 20% ownership and undertake the role of development manager. Capital Hills will establish and manage the fund.
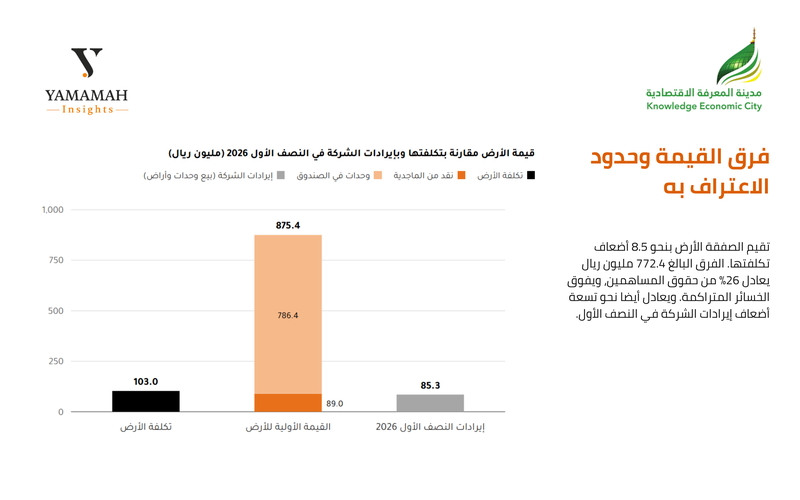
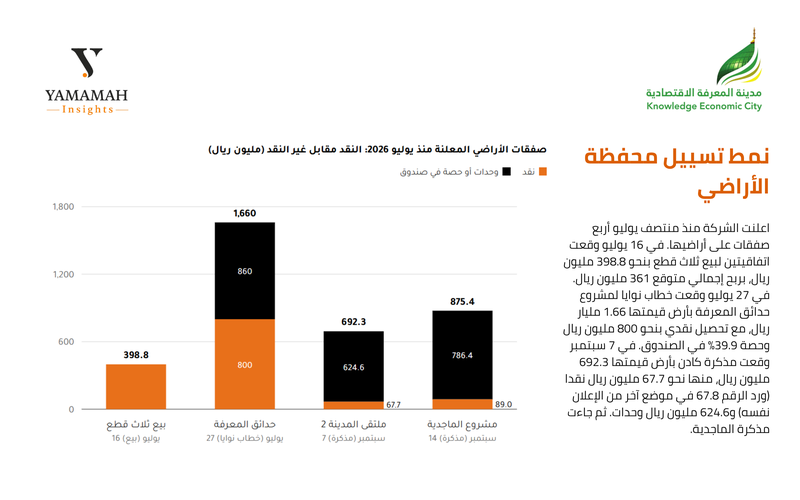
The company outlined the financial impact of the deal: the initial value of the project land is approximately SAR 875.4 million (while its approximate cost is SAR 103 million). Following the execution of the final agreements, the company will receive SAR 89 million in cash, paid by Al-Majdiah, in addition to investment units in the fund valued at SAR 786.4 million.
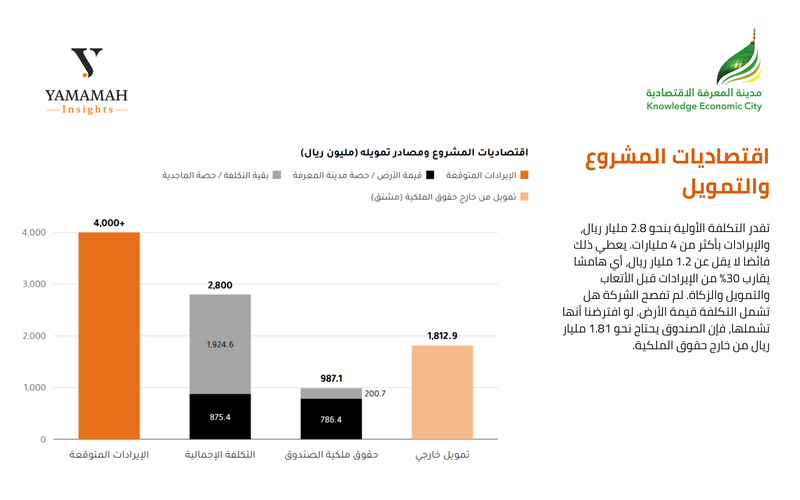
Knowledge Economic City indicated that the project will be built on an area of 97,000 square meters and will include approximately 2,700 residential apartments and a commercial component, with an initial total cost estimated at approximately SAR 2.8 billion and expected revenues exceeding SAR 4 billion. The project primarily targets non-Saudi Muslim customers, in line with the Non-Saudi Ownership of Real Estate Law and the objectives of Vision 2030.
Amid the monetization of real estate assets and the formation of strategic partnerships, students of Al Yamamah University discussed the dimensions of this memorandum and its financial and operational implications for the company's performance and the future of urban development in Medina, as follows:
Partnership Model and Balancing Supply and Demand
Student "Yazan Al-Hamoud" @Yazan Hamoud shared his analytical reading, saying: "I believe the partnership model is appropriate because it allows the company to benefit from the value of the land without bearing the full cost of development and financing.
The significant difference between the land's cost and its current value may support the financial statements in the future, but it is not recorded as an immediate profit; rather, it depends on the accounting treatment.
Targeting non-Saudis will also increase demand and attract new liquidity to the city, while ensuring that supply growth remains balanced to prevent price inflation."
Reducing Financing Burdens and Accounting Gains
Student "Rand Al-Khalaf" @Rand Alkhalaf explained: "This partnership helps develop the project without bearing the full financing and development costs.
The substantial difference between the land's cost and its value lays the groundwork for capital gains. However, the final profit will depend on the accounting treatment and completion of the deal, which will support real estate investment whenever supply and demand are balanced."
Optimal Asset Utilization and the Importance of Execution
Student "Mohammad Al-Ghaihab" @Mohammad Alghaihab offered a strategic view, saying: "The key point here is not the valuation difference itself, but how the company utilizes its assets. Instead of exiting and selling for a one-time gain, it has taken a stake in the fund to participate in project returns exceeding SAR 4 billion.
The project's success will maximize the company's benefit, making execution and actual sales far more important than current valuations."
Asset-Light Model and Accounting Recognition Requirements
Student "Fahad Al-Shaibani" @Fahad Alshaibany said: "The deal reflects a smart approach to land utilization through an (Asset-Light) development model. From a financial perspective, the accounting difference between the cost (SAR 103 million) and the initial value (SAR 875.4 million) amounts to SAR 772.4 million. However, it cannot be considered a realized profit immediately, because accounting recognition depends on (IFRS) requirements and completion of the transfer of ownership."
Accelerating Execution and Cash Flow Flexibility
Colleague "Lujain Al-Qurashi" @Lujain Algorashi shared her analysis, saying: "The partnership model provides an opportunity to benefit from the land's value without bearing the full costs, while bringing in specialized partners will accelerate execution and preserve cash flow flexibility.
The significant valuation difference for the land draws attention to the expected financial impact when the fund is activated, noting that targeting non-Saudis will attract new financial inflows supporting the construction and services sectors."
Governance and Legal Structuring of Non-Saudi Ownership
From a legal and regulatory perspective, student "Ryouf Al-Suwailem" detailed the implications, saying: "The memorandum of understanding (MoU) is a non-binding framework until the final contracts and Capital Market Authority approvals are obtained.
Since the regulations prohibit direct ownership by non-Saudis within the city's boundaries, the targeting relies on usufruct or investment mechanisms through fund units as securities. This requires precise contractual regulation that protects ownership of the asset and defines liquidation and profit-distribution mechanisms."
Immediate Liquidity and Attracting Foreign Investment
Student "Fay Al-Dosari" @Fay Aldossari explained the benefits of the structure, saying: "The (Asset-Light) model provides the company with immediate liquidity and avoids loans, while recording excellent capital gains immediately upon transferring the asset to the fund.
Economically, supplying 2,700 apartments to non-Saudis will attract foreign capital directly, stimulating the retail sectors throughout the year and achieving balance through an organized real estate product."
Supporting Cash Liquidity and Monitoring Profit Margins
Student "Arwa Al-Huwaiti" @Arwa Alhuwaiti confirmed: "The company's receipt of SAR 89 million in cash will support liquidity and reduce the need for direct financing for a project costing SAR 2.8 billion.
But what matters most to me is monitoring profit margins and actual cash flows as execution progresses, because higher expected revenues do not necessarily mean higher profitability."
Capital Gains and Capturing Foreign Demand
Student "Amal Mansi" @Amal Mansi described the deal, saying: "The deal is a financial masterstroke. It transforms land costing SAR 103 million into an asset valued at SAR 875.4 million, generating capital gains of approximately SAR 772 million. Relying on this model ensures accelerated construction without financing burdens and captures inelastic demand that guarantees sustainable foreign financial inflows."
Valuation Difference and Timing of Accounting Recognition
Student "Al-Batool Bedairi" @Albatool Bedairi added: "The substantial difference between the cost and initial value reflects a significant increase in the asset's value, but it does not mean that profit will be recorded immediately. The accounting treatment is linked to the company's percentage of ownership and control over the fund and the conditions for transferring the land, making the timing of accounting recognition the decisive factor affecting earnings."
Expanding the Demand Base and Investment Attractiveness
Student "Rahaf Al-Anazi" @Rahaf Alanazi shared her view, saying: "The partnership represents a good opportunity to generate cash flows from the deal and reduce development costs. Targeting non-Saudis will expand the demand base and increase the attractiveness of real estate investment, while outcomes will remain tied to the speed of actual execution."
Cash Return and Real Estate Market Stability
Student "Jumana Al-Shahri" @Jumana Alshehri said in her analysis: "The company benefits from development without bearing debt burdens and achieves a direct cash return. The valuation difference will have a positive impact upon accounting recognition, and adding 2,700 apartments will meet the expected increase in demand from non-Saudis and help achieve supply-and-demand balance."
Strategic Alliances and Reducing Financial Risks
Student "Fahad Al-Ruwaished" @Fahad Alruwaished praised the move, saying: "The company's adoption of this model is an excellent step. Direct cash collection supports liquidity, while bringing in strong partners such as (Al-Majdiah and Capital Hills) accelerates development and spares the company heavy debt and financing costs. This allows the company to enhance its assets while retaining an 80% stake from which it can earn excellent returns."
Retaining a Majority Stake and Service Integration
Student "Rimas Al-Mashali" @Rimas Almashali explained: "The partnership provides an opportunity to develop the land while retaining a large stake (80%) in the fund. Targeting non-Saudis will strongly support demand, particularly given the project's location and the integration of its accompanying services."
Estimated Land Value and the Test of Actual Sales
Student "Ghadah Al-Wallan" @Ghadah Alwallan focused on actual results, saying: "The key point is the increase in the estimated land value, which will have a positive impact once the accounting requirements are completed and ownership is transferred. However, the actual and final impact depends on successful sales and revenue generation, not merely on the initial valuation."
Time Value of Returns and Collection Speed
From an efficiency perspective, student "Mohammad Al-Mudbil" @Mohammed Almudbil analyzed the time factor, saying: "The difference between cost and revenues appears large, but the feasibility assessment depends entirely on the timing of realizing returns. A project of this size may extend over several years, so sales and collection speed is the true test. Achieving a substantial return within three years is entirely different in financial value from achieving it over eight years."
Opportunity Cost and Stability of Financing Flows
Student "Ahmed Al-Jadaan" @AHMED ALJADAAN supported this view, adding: "Distributing returns over long periods reduces the time value of money and increases exposure to opportunity cost and inflation rates. The strength of the deal lies in selecting Al-Majdiah to reduce delay risks and having Capital Hills ensure the stability of financing flows. Accurate valuation ultimately depends on the cash-flow schedule and presales."
Converting Assets into Projects and Price Balance
Student "Thanaa Al-Shayib" @Thanaa Alshayib concluded the analytical discussion, saying: "This partnership is a smart step toward converting assets into actual projects at the lowest financing cost. The valuation difference will have a positive impact after the accounting requirements are met, and targeting non-Saudis will open a new source of demand that attracts liquidity and investment, while its impact on the balance of real estate prices in the area must be monitored."
Three-Way Alliance to Develop a Real Estate Project in Medina at a Cost of SAR 2.8 Billion
Expert Abdulaziz Khrais commented, outlining the key details and dimensions: "There is a three-way alliance bringing together two listed companies. Al-Majdiah, Knowledge Economic City, and Capital Hills have signed a memorandum of understanding to develop a residential and commercial real estate project in Medina.
According to the available data, the memorandum of understanding is valid for 90 days, while the project's initial total cost is approximately SAR 2.8 billion.
Regarding Al-Majdiah: ownership will be distributed as 80% for Knowledge Economic City and 20% for Al-Majdiah. Al-Majdiah's total contribution is approximately SAR 200.7 million, including SAR 89 million to purchase a corresponding stake in the land and SAR 111.7 million paid in cash into the fund structure according to the payment schedule specified in the memorandum. Al-Majdiah aims to expand its presence in Makkah and Medina. It previously announced the Mishraf Al-Majdiah project in Medina, its work at Masar destination, and its participation in an alliance to develop the East Hindawiyah project in Makkah.
Regarding Knowledge Economic City: the company stated that expected revenues exceed SAR 4 billion. It will receive approximately SAR 89 million in cash in addition to units in the target fund valued at SAR 786.4 million in exchange for contributing the land as an in-kind contribution to the fund. The project is located within Knowledge Economic City, on a plot of approximately 97,000 square meters, and comprises approximately 2,700 varied residential apartments, with a commercial component on the ground floor offering approximately 8,000 square meters of net leasable area, in addition to more than 3,500 parking spaces. The project will focus on non-Saudi Muslim customers in accordance with the Non-Saudi Ownership of Real Estate Law."
Project Dimensions and Its Impact on Financial Performance
In an analytical reading, financial and economic analyst "Hamad Al-Saeed" @Hamad Alsaeed adds: The memorandum of understanding between Knowledge Economic City and Al-Majdiah reflects a shift in the company's business model. After relying on unit sales, the company is moving toward monetizing its land portfolio through real estate funds. The land was initially valued at approximately SAR 875 million against a cost of SAR 103 million, a value that remains subject to due diligence. However, direct cash amounts to no more than SAR 89 million, while the majority of the value is tied to project execution and unit sales.
In this context, the accounting treatment remains the decisive factor in interpreting the financial impact. Consolidating the fund could add significant liabilities to the company's balance sheet without recording a profit. The equity method would limit the recognized profit and would not eliminate accumulated losses.
On the other hand, the project is based on demand from a new segment enabled by the Non-Saudi Ownership of Real Estate Law, in an area where residential supply and demand are both increasing.
Accordingly, we believe the deal's actual value will be determined by the execution of the final agreements and the pace of sales, not by the figures announced at signing.

Comments (5)
No comments yet. Be the first to comment!