

United Cooperative Insurance Company has reached a critical juncture in its legal and financial proceedings following a court ruling to commence liquidation proceedings and reject its application for financial restructuring, with the company’s assets handed over to the appointed liquidator.
The court ruling follows a sharp increase in accumulated losses to SAR 459.57 million, exceeding 115% of the company’s capital, as well as escalating regulatory penalties that halted its operations and put pressure on its financial solvency. In response, the company’s management plans to file a formal appeal before the Court of Appeal in a final attempt to halt the liquidation proceedings.
Students from Al Yamamah University discussed the legal and financial dimensions of the case and its implications for the rights of shareholders and creditors, as follows:
The impact of judicial liquidation and the challenges of financial restructuring
Student “Albatool Bedairi” @Albatool Bedairi shared her analysis: “The course of the case reflects the progressive regulatory approach to addressing financial distress, with penalties and attempts at remediation preceding liquidation. If the appeal is accepted, a return to operations will still depend on addressing the causes of the distress, demonstrating financial solvency, and obtaining the necessary approvals from the Insurance Authority.”
Distribution of proceeds and limits on shareholders’ financial liability
Student “Rabiah Almugait” @Rabiah Almugait explained the order of repayment: “Liquidation protects creditors’ rights and organizes the company’s financial affairs, as asset proceeds are distributed according to statutory priorities. If the assets are insufficient, shareholders bear the loss only up to the value of their investment, while remaining debts are handled under the Bankruptcy Law.”
Early intervention and future financial regulation
Student “Dina Alarjani” @Dina Alarjani shared her perspective: “This case underscores the importance of early intervention before losses worsen. Liquidation limits the damage and ensures that outstanding obligations are paid in order of priority, while reviving operations after an appeal would require a realistic plan and adequate financing.”
An analytical look at the timing of decisions and the financial position
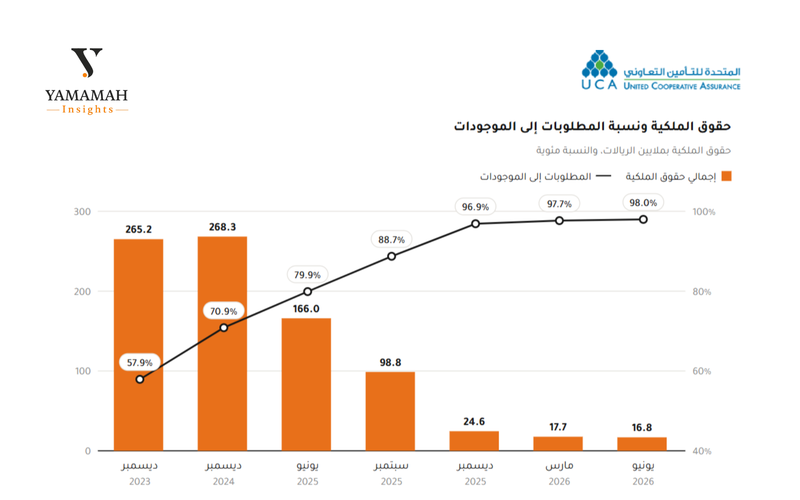
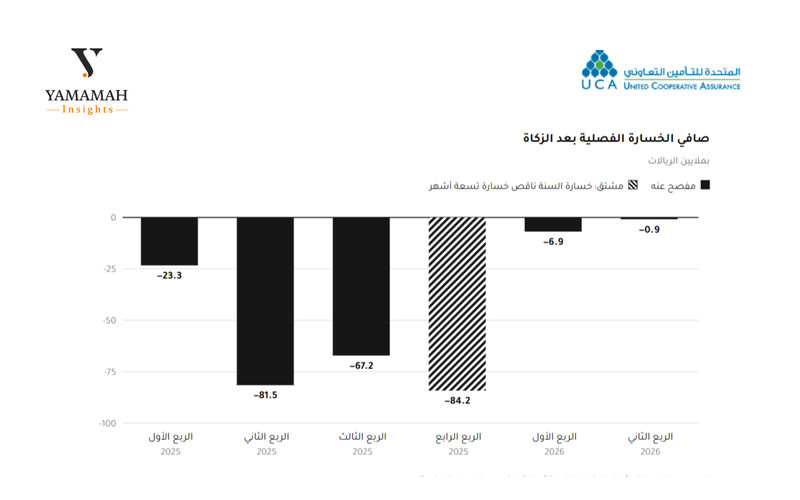
Offering a different view, student “Jana Aljebali” @Jana Aljebali said: “The measures were not taken early enough. Losses for the first three quarters of 2025 accumulated to SAR 172 million before the suspension. Although the second-quarter 2026 loss fell to SAR 0.9 million, that is not enough for a recovery, given the erosion of equity to SAR 16.8 million and the fact that liabilities reached 98% of assets.”
Completing the bankruptcy process and protecting market participants
Student “Noof Alanazi” @Noof Alanazi discussed the repayment mechanisms: “Liquidation gives creditors priority, and the Bankruptcy Law governs any remaining financial shortfall. Shareholders, meanwhile, face the loss of their entire investment, which makes it essential to demonstrate overall financial capacity when seeking to resume operations.”
The company’s ongoing obligations to policyholders
Student “Yazan Hamoud” @Yazan Hamoud explained the operational scope of liquidation: “Liquidation does not extinguish policyholders’ rights or their valid claims. The company’s assets are distributed to creditors first, meaning a shareholder’s maximum loss is the full value of their investment, with no additional financial liability.”
The importance of early liquidity in addressing accumulated losses
Student “Rand Alkhalaf” @Rand Alkhalaf added further context on the financial shortfall: “This case demonstrates the need to address financial distress before accumulated losses reach 115% of capital. Resolving the crisis is directly linked to providing liquidity and complying with regulatory requirements.”
The legal classification of debts and shareholders’ liability
Colleague “Lujain Algorashi” @Lujain Algorashi highlighted the order of claims: “Liquidation establishes the order in which creditors are repaid without converting the financial shortfall into a personal liability for shareholders. Overturning the ruling would also require a fundamental solution to the causes of operational distress.”
Protecting investors’ personal assets
Student “Rahaf Alanazi” @Rahaf Alanazi emphasized the legal implications: “Liquidating the assets is intended exclusively to meet outstanding obligations. A shareholder’s loss is limited to the value of their shares, without affecting their personal assets, while a return to operations would require regulatory safeguards.”
Progressive penalties and the allocation of shortfalls among creditors
Student “Meshail Alanazi” @Meshail ALANazi described the regulatory framework: “The shift from regulatory penalties to liquidation reflects a gradual approach aimed at protecting creditors. Creditors bear any shortfall under the Bankruptcy Law, while a shareholder’s liability remains limited to the value of their shares.”
Structural interventions to limit financial repercussions
Student “@Thanaa Alshaib” asked what could have been done earlier: “The problem lies in how the losses were handled before they worsened. Liquidation is the last resort for protecting rights, even though the company has valuable assets that may still be insufficient to satisfy shareholders’ claims.”
Priorities and pro rata distribution among creditors
Student “Ahmed Al-Jadaan” @AHMED ALJADAAN explained how the proceeds are distributed: “The Bankruptcy Law applies a strict order, beginning with secured debts and then employees’ claims, followed by ordinary creditors, who divide the remaining proceeds pro rata, while shareholders receive zero riyals.”
New capital requirements for resuming operations
Student “Shahad Alkhamis” @Shahad Alkhamis highlighted the challenges ahead: “The regulatory approach was logical, but resuming operations requires an injection of new capital and regulatory confidence—both extremely difficult to achieve in the current circumstances.”
The legal basis of bankruptcy priorities and corporate legal personality
Student “Fahad Alruwaished” @Fahad Alruwaished analyzed the court ruling: “The proceeds are distributed to cover liquidation fees, preferential debts, and policyholders’ claims. With accumulated losses reaching SAR 459.57 million, uncovered debts are written off and the company’s legal personality comes to an end, without requiring shareholders to pay any additional amounts.”
Maximum financial risk and conditions for resuming operations
Student “Fay Aldossari” @Fay Aldossari outlined the limits of shareholders’ exposure: “A shareholder’s maximum loss is the share falling to SAR 0. If there is a shortfall, creditors are paid pro rata, while resuming operations would require an injection of liquidity sufficient to reduce losses to below 50% of capital and meet the solvency margin requirement.”
Why liquidation is a reasonable way to protect creditors’ rights
Student “Jumana Al-Shehri” @Jumana Alshehri said the decision was realistic: “Liquidation is a reasonable option for protecting creditors after losses exceeded 115% of capital. A shareholder’s direct loss remains tied to the value of their original investment.”
The financial gap and transfer of authority under the court ruling
Student “Dana Al-Sadoun” @Dana Al-Sadoun described the consequences of the ruling: “Full authority has been transferred to the liquidator to begin selling assets and protect creditors. This makes appealing to the Court of Appeal less likely to succeed, given the size of the financial gap.”
Governance and management accountability in cases of financial distress
Student “Zaid Darweesh” @Zaid Darweesh explained the legal standards: “Priority goes to policyholders and creditors, and any remaining shortfall is written off under the law unless negligence or misconduct by the company’s management is established. If an appeal is filed, strong financial guarantees must be provided.”
Financial statement analysis and the strength of the company’s financial position
Student “Ghadah Alwallan” @Ghadah Alwallan drew attention to the financial indicators: “The quarterly loss falling to SAR 0.9 million in the second quarter of 2026 does not mean the company has recovered, given the erosion of equity and the fact that liabilities account for 98% of assets. The company must therefore be assessed based on the strength of its financial position.”
Regulatory effectiveness and requirements for an appeal
Student “Ryouf Alsewailim” @Ryouf Alsewailim concluded the discussion: “The progressive regulatory response reflects the effectiveness of the regulatory environment in protecting creditors. The chance of overturning the ruling still depends on submitting a remediation plan and restoring financial solvency by injecting new capital.”
United Insurance faces a dark path after its financial restructuring application is rejected
Expert Abdulaziz Khrais believes the company has entered a dark period after receiving a letter from the court stating that its application to commence financial restructuring proceedings had not been accepted.
Khrais explained that the company sought financial restructuring to avoid liquidation, following an application by one of its creditors that the court approved.
Asked, “What will happen to the company?” he said the outcome was unclear and the risk to shareholders was very high. The company’s shares had been suspended by the Capital Market Authority until the situation became clear and the company’s future was determined, whether through liquidation or financial restructuring.
The company’s financial position is poor, with accumulated losses equal to 115% of its capital. In addition, the Insurance Authority ordered it to stop issuing or renewing insurance policies for all insurance products, including those offered to individuals and extended warranty products, effective September 22, 2026, due to violations of supervisory and regulatory instructions.
How the financial position affects liquidation and shareholders’ rights
In an analytical assessment, financial and economic analyst “Hamad Alsaeed” @Hamad Alsaeed added: The ruling to commence liquidation proceedings for United Cooperative Insurance is an example of how financial distress at insurance companies becomes evident in the statement of financial position long before it reaches court. The company’s liabilities have grown by 124% since the end of 2023, compared with 32% growth in its assets. As a result, equity now covers just 2% of assets, while accumulated losses reached 115% of capital at the end of June 2026.
As for operations, written premiums fell by 98.5% in the second quarter of 2026 following the suspension of new policy issuance ordered by the Insurance Authority for regulatory violations. This means that continuing operations depends on correcting those violations and strengthening the company’s capital.
In our assessment, the ruling is consistent with what the financial statements show, and little, if anything, is likely to remain for shareholders after creditors are paid. The next steps are expected to be determined by the liquidator’s report on asset and debt values and the outcome of any appeal before the Court of Appeal.

Comments (4)
No comments yet. Be the first to comment!