
Jarir Marketing Company announced its estimated financial results for the period ending on June 30, 2026 (the first half); where net profit for the period increased by 17.97% to reach 489 million riyals, accompanied by sales growth of 10.81% to reach 5,812.5 million riyals thanks to the growth in sales of most departments, especially smartphones and the strong performance of Gulf branches.
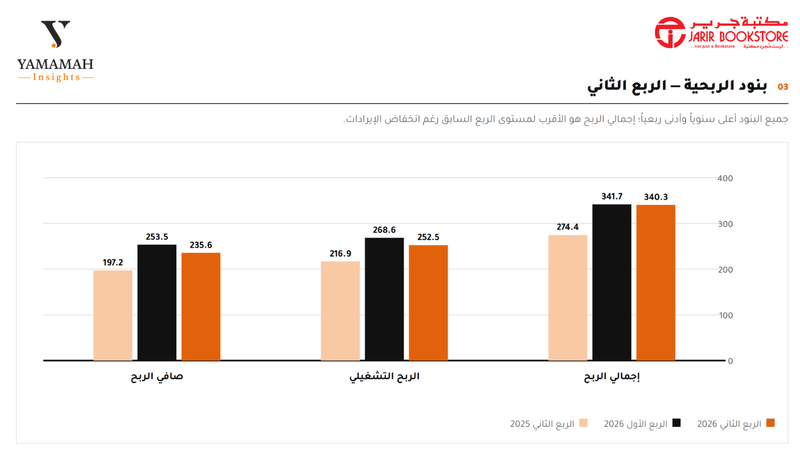
In terms of the current quarter compared to the same quarter last year, the company recorded a net profit of 235.6 million riyals, an annual increase of 19.47% due to a 24% growth in gross profit supported by improved profit margins and no reliance on promotional discounts due to scarcity of supply, and improvement in the sales mix of high-profit departments such as school supplies and books.
Compared to the previous quarter, sales decreased by 8.70% to record 2,774 million riyals affected by a decline in smartphone sales after achieving record numbers in the previous quarter, which led to a 7.06% decrease in net profit due to increased selling, marketing, and general and administrative expenses, while this period witnessed operational expansion through the opening of three new showrooms in Medina, Al-Baha, and Riyadh, and the opening of two alternative showrooms in Kuwait and Jeddah.
Students from Al Yamamah University discussed the implications of these results, the drivers of sales growth, and the impact of operational expansion on profit margins as follows:
Margin Efficiency and Sustainability Challenges
Student “Ghadah Alwallan” @Ghadah Alwallan opened the analysis by saying: "In my opinion, what stands out in Jarir's results is that the improvement was not limited to sales growth, but also included margin improvement; because gross profit grew faster than revenues, which reflects the company's benefit from not being pressured on prices due to scarcity of some products, but the important question is: Is this margin improvement sustainable if offers and discounts return strongly?"
Therefore, in my opinion, the assessment of performance in the second half depends on the company's ability to balance expansion and opening showrooms while maintaining the same profitability efficiency, especially since expansion may increase sales but also puts pressure on operating expenses".
The Impact of External Expansion and Risk Management
Student “Rimas Almashali” @Rimas Almashali commented: "I see that the improvement in profit margins is mainly related to the scarcity of supply and the reduction of promotional offers, so its continuation depends on the market situation in the coming periods.
Moreover, expansion in the Gulf supports sales growth, but the impact of currency fluctuations in Egypt highlights the importance of balancing growth opportunities with risks. Regarding the opening of new showrooms, it is expected to support sales if demand continues at current levels, while it is necessary to monitor its impact on operating expenses during the second half of the year".
Operational Efficiency and Supply Chain Stability
Student @شهد المحيسن continued the analysis by saying: "In my opinion, Jarir's results reflect clear operational efficiency, but the sustainability of current profit margins depends on the stability of supply chains and the return of competition in the market, so they may not remain at these high levels forever. As for external expansion, it provides the company with good growth opportunities, but it requires effective management of currency fluctuations risks, as seen in the Egyptian market. Regarding the opening of new showrooms, I see it as a well-considered investment that may temporarily increase operating expenses, but it supports sales growth and enhances the company's profitability in the long term if the locations with high returns continue to be chosen".
Positive Pricing and the Showroom Establishment Phase
Student “Mohammad Alghaihab” @Mohammad Alghaihab shared his opinion saying: "What caught my attention the most is the increase in profit margins even though sales did not rise at the same rate, which indicates that the company was able to sell at better prices and maintain its profitability without entering into strong discounts.
However, in my opinion, it is difficult to say that this is sustainable, as it is linked to current market conditions, and if competition returns or offers increase, margins may revert to their normal levels.
As for expansion, I see it as a positive step if it is in areas with demand, especially since Jarir is well-known and has a strong base.
It is natural for some expenses to rise initially, but if the new showrooms achieve good sales, they will cover these costs over time, and this will positively reflect on profits".
Dissecting Profit Sources and Expense Gap
Student “Sara Alaqeel” @Sara Alaqeel concluded the analysis by saying: "Profitability grew faster than sales noticeably, but this growth is composed of three sources of varying quality; the first is the scarcity of supply, which is a temporary condition, the second is the improvement in the sales mix, which is seasonally recurring but not permanent, and the third is the efficiency of Gulf branches, which is closest to a sustainable competitive advantage.
The main point of concern is the widening gap between gross profit and net profit due to increased selling, marketing, and administrative expenses, coinciding with the opening and replacement of showrooms within just six months.
There is a confirmed official point represented in the currency differences specifically related to the subsidiary company in Egypt as a separate accounting exposure. The upcoming test in the third quarter will determine whether the improvement in gross margin is structurally permanent or a cyclical peak related to market conditions".
Profits Exceed Expectations and Restore Investor Confidence
Expert Abdulaziz Khrais commented on the financial results saying: "Jarir Company recorded profits of 235.6 million riyals for the second quarter of 2026, exceeding the average expectations of analysts, which were at 221.8 million riyals.
In terms of comparison with the same quarter, the company recorded its best profits in its history, growing by 19.5% compared to the same quarter due to increased sales in most departments, especially the smartphone department, and the company benefited from the inventory of goods it built up in previous periods and the quality of its logistics system, especially with the increase in imports due to the Strait of Hormuz crisis.
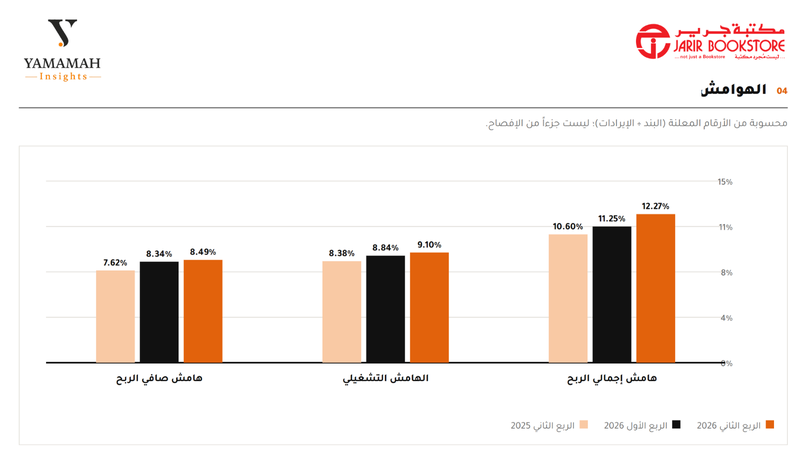
In terms of the period, profits increased by 18% compared to the same period last year due to the increase in gross profit resulting from improved profit margins as the company did not offer promotional discounts at reduced prices compared to the previous year amid the scarcity of product supply as stated by the company.
It is worth noting that the company's stock recorded remarkable increases during the past period, reaching its highest levels in four years, with a notable increase in the percentage of foreign ownership, indicating that the company has gained the trust of its investors during the past period".
Reading on Operational Flexibility and Expansion in Profit Margins
In an analytical reading of the company's performance, financial and economic analyst “Hamad Alsaeed” @Hamad Alsaeed stated: The financial results of Jarir Company for the second quarter of 2026 showed strong performance that exceeded expectations, as the company achieved a net profit of 235.6 million riyals, growing by 19.5% year-on-year, alongside revenues of 2,774 million riyals (growing by 7.2%). This positive fundamental variance reflects a noticeable improvement in operational efficiency and an expansion in overall profit margins, driven by the company's success in managing inventory with high flexibility and efficiently adapting to supply and demand dynamics.
However, we see that this exceptional expansion in gross profit margin to reach 12.3% is mainly due to temporary market conditions represented in the regional supply shortage of some products, which reduced the intensity of promotional pressures.
Therefore, we expect these margins to trend towards gradual moderation with the return of supply chains to normal and the stabilization of price competition. Despite the pressures resulting from increased selling, general, and administrative expenses, achieving a net profit with this growth (19.5%) enhances the positive outlook for the company's financial solvency and its ability to sustain attractive cash dividends.
Structurally, the income statement shows a clear pressure on implicit operating expenses that grew at a faster pace than revenue growth of 7.2%. This disparity represents a temporary decline in spending efficiency due to the five new and alternative showrooms bearing their full operating expenses and depreciation immediately upon launch and before their sales mature.
Disclaimer: (This material was prepared under the supervision of the “Yamamah Insights” editor and with the assistance of artificial intelligence tools for financial education purposes, and it does not constitute a recommendation to buy, sell, or hold any security, and it reflects the opinions of its authors and not the platform's opinion).
 Ask Yamami

Comments (5)
No comments yet. Be the first to comment!